Sentora’s Shaky Deal with Aave: Who Gets the Cash?
Sentora Takes the Wheel
So, here’s a little something that’s been stirring the pot in the DeFi world: Sentora has just decided to split Aave revenue right down the middle. That’s right, 50% to Sentora and 50% to the Aave DAO. Sounds like a fairytale, huh? But wait, there’s a catch — the suppliers are the ones who have to absorb all the losses. And you thought your roommate’s pet iguana was a problem!
The Power Shift
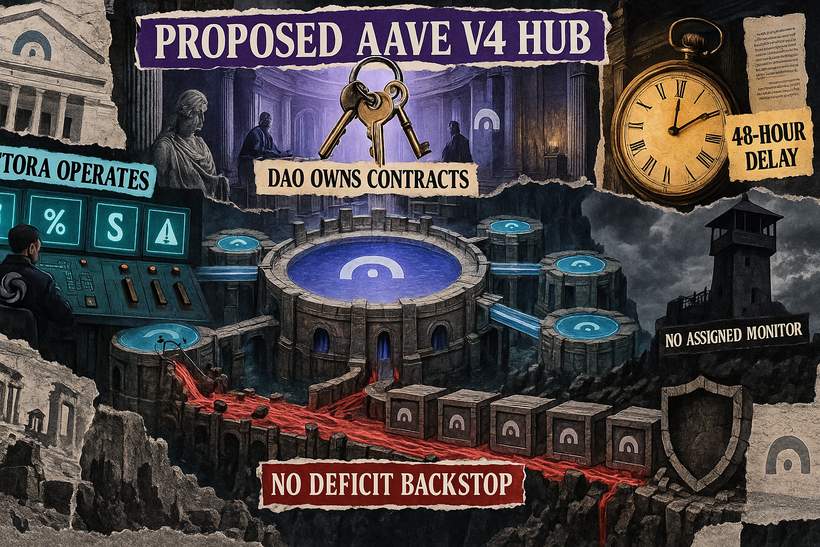
Aave DAO, in all its glory, will own the contracts for a shiny new Ethereum lending market, while Sentora plays the role of decision-maker extraordinaire. This governance proposal took to the virtual stage on September 28, where our hero, Sentora, sought to manage an isolated Aave V4 Hub and its lending Spokes through revocable roles. Think of it like a magic show, only instead of rabbits, it’s all about credit risks.
All Eyes on Sentora
With this risky game, Sentora gets to decide on everything from collateral to interest-rate curves, giving them the reins while leaving Aave’s risk service providers hanging out to dry. They’ll still own the market but have no say in the day-to-day drama. It’s like your cat owning the house but you pay for all the treats!
The Voting Game
Now, hold your horses! This proposal is still just an ARFC, meaning everyone gets a chance to weigh in before it goes to vote. First up is a Snapshot vote, followed by an on-chain Aave Improvement Proposal – the whole shebang before any final nod.
Hub and Spokes, Who Dis?
Aave V4 is like a well-crafted donut: you have the liquidity Hub that holds the sweet stuff and the Spokes that serve up the loans. Sentora wants its very own Ethereum Hub for these Spokes, with no credit lines from other Aave DAO Hubs. Think of it as cutting off the family credit card but still sending money to the relatives.
What Can You Borrow?
Aave’s proposal is only letting you borrow some particular assets – RLUSD, PYUSD, and OUSD. Sorry, no USDC or USDT allowed! It’s like a club where only VIPs are getting in, and you’re not on the list.
Authority Shows Its Face
Now, Sentora won’t hold any contracts; it’ll just manage the markets. Yet, a big ol’ Governance Short Executor from the DAO will keep the admin roles in check. Imagine it as the strict parent who holds all the keys while the cool older sibling (that’s Sentora) drives the family car.
Timing Is Everything
Different action times are added to the mix like odd slices of pizza. There’s a 48-hour delay for risk increases and other functions that you won’t want to miss. So if you’re waiting for a big move, well, you’ll have to bite your nails for a couple of days.
Oh, the Objections!
In the wacky world of DeFi, if someone spots a problem with a new Hub or collateral asset, they can put up a little stink and stop the plan via a Snapshot vote. But here’s the kicker: no one is actually getting paid to keep an eye on things. So good luck spotting any issues!
Who Will Cover Your Losses?
Let’s clarify — if a poor lil’ borrower runs out of collateral, the Hub has to lick its wounds and report any shortfall. But if the loss hits, it’s the suppliers who have to swallow the hard pill. What a wild ride!
Money Matters
The proposal is giving Sentora half of that sweet protocol revenue pie – that includes reserve-factor earnings and fees from protocol liquidations. It’s like winning a jackpot but also knowing you might have to give it all back! Sounds fun, right?
Pondering Safety Nets?
Before any grand plans are put into action, the DAO has to decide whether Sentora can operate with no independent watchdog. It’s a bit like letting a toddler run a candy store.
Final Words
When the dust settles, prospective suppliers will throw their chips in based on asset lists and oracle choices, all while wondering how to protect themselves from potential losses. Time will tell if this partnership is a match made in DeFi heaven or a disastrous adventure!